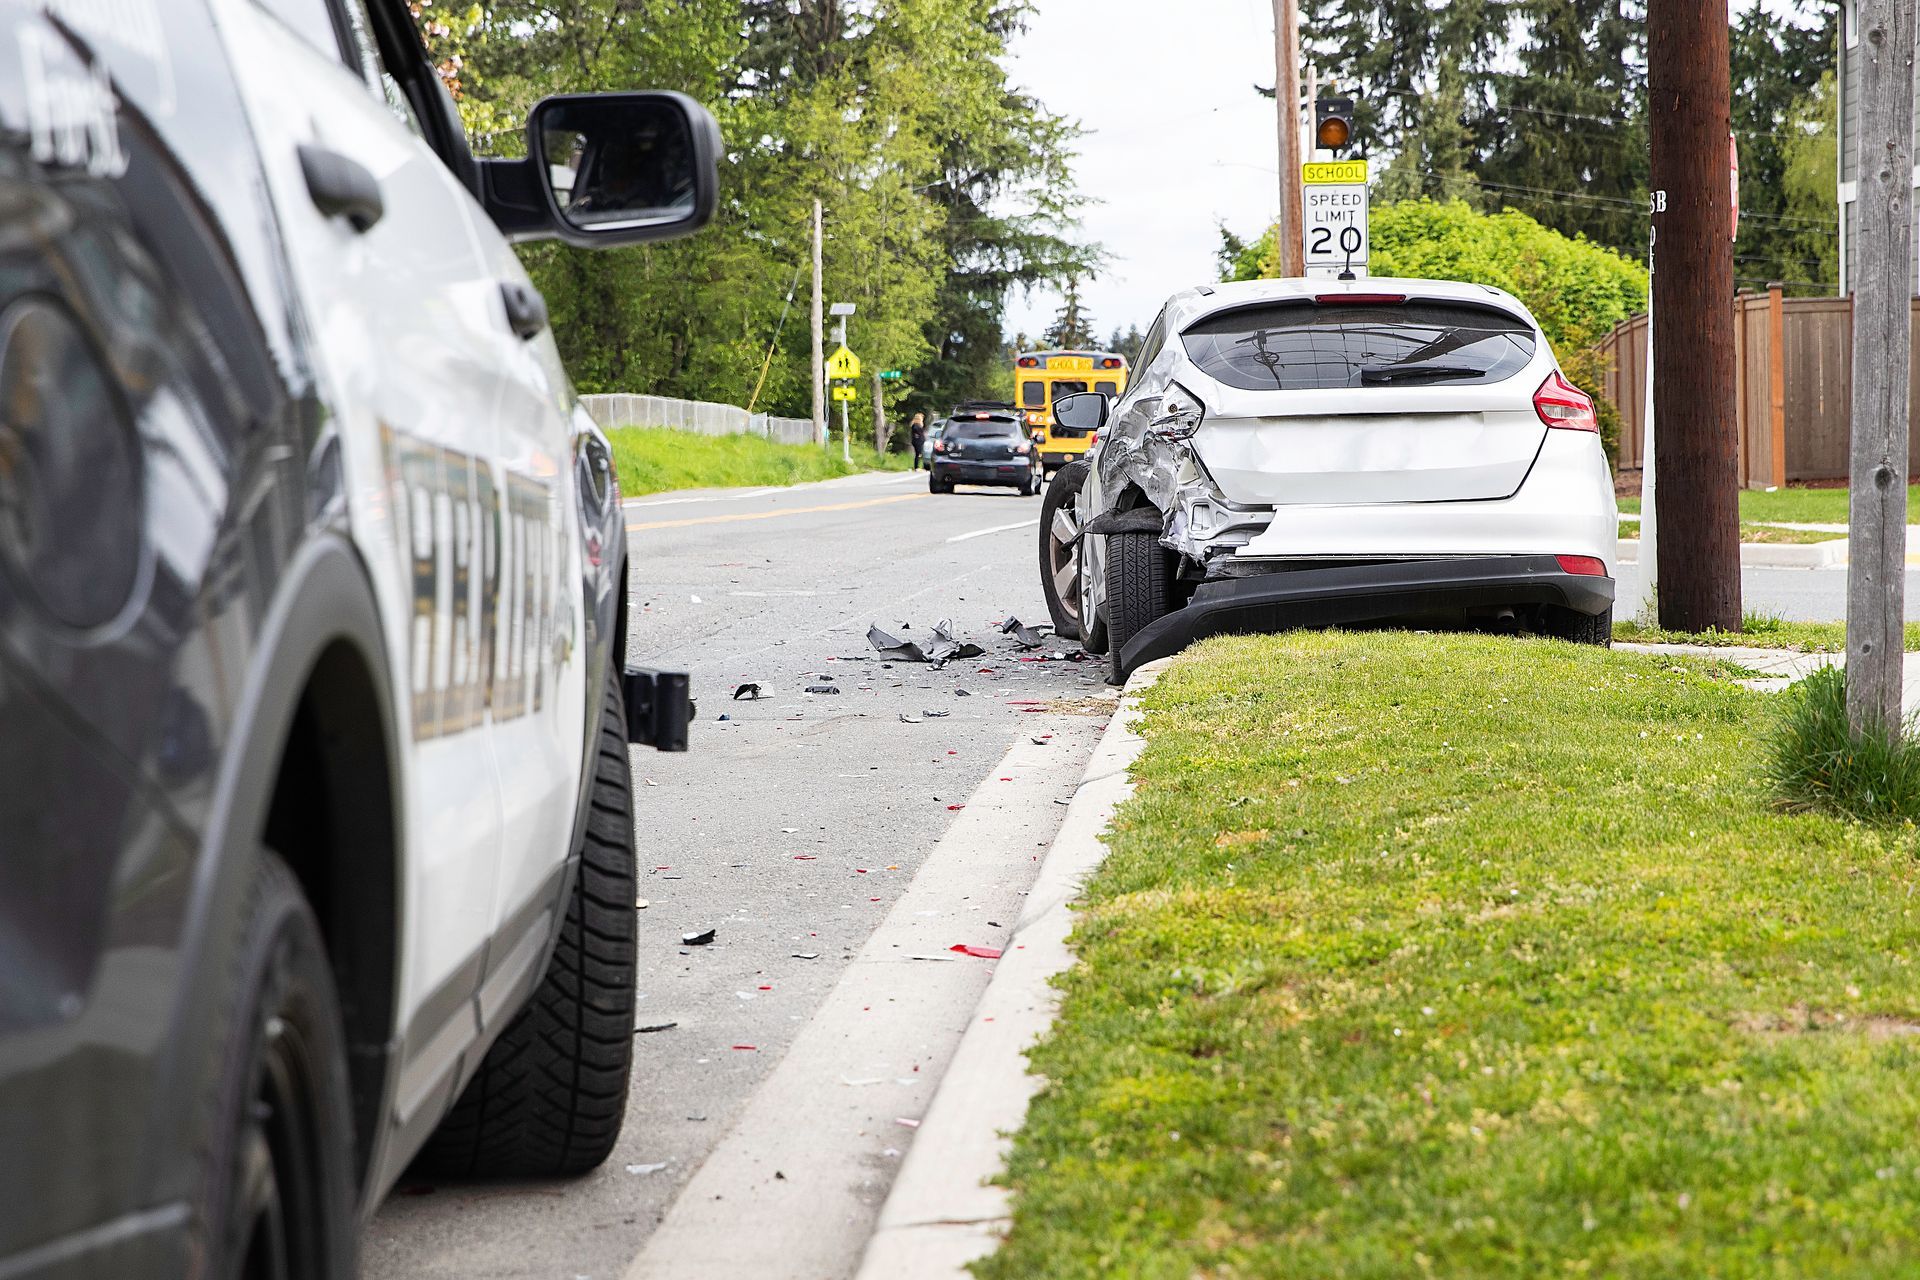
Chicago Hit and Run Lawyer for Uninsured and Underinsured Motorist Claims
When the driver who hit you left the scene or carried the state minimum, the claim moves onto your own policy, and we build it on the Illinois statutes that treat a car nobody can find as an uninsured car, before the deadline buried in that policy closes the claim for you.
Call (312) 492-7700 or email
info@lsblaw.net to talk through your coverage today.
Under Illinois Law, the Car That Fled Is an Uninsured Car
Every auto liability policy issued in Illinois has to carry uninsured motorist coverage at the bodily injury minimums set by Section 7-203 of the Illinois Vehicle Code, which are $25,000 per person and $50,000 per accident (215 ILCS 5/143a). That same statute treats a hit-and-run vehicle as an uninsured motor vehicle. The driver disappeared. Your coverage did not.
Section 143a does four things that decide how your claim is handled:
- It requires uninsured motorist coverage on every Illinois auto liability policy, at $25,000 per person and $50,000 per accident.
- It treats a vehicle that leaves the scene as an uninsured motor vehicle, so the claim proceeds even though the driver is never identified.
- It sends disputes over coverage and over the amount of your damages to arbitration before the American Arbitration Association.
- It limits property damage recovery to damage caused by actual physical contact with the uninsured vehicle.
This page covers the coverage side of a Chicago crash. Liability, medical bills, lost income and the rest of what a crash claim involves are handled on our
Chicago auto accident page.
Uninsured and Underinsured Are Two Different Problems
These two situations get treated as one idea almost everywhere, and they are governed by separate statutes that pay out in different ways. Which one you are in changes the order the claims have to be handled and how much of the recovery you keep.
When the driver had a policy far smaller than your bills
Underinsured motorist coverage is governed by 215 ILCS 5/143a-2. For policies issued or renewed on or after December 1, 2004, it must be provided in an amount equal to your uninsured motorist coverage wherever that coverage exceeds the Section 7-203 minimums. It fills the gap up to your own limit, and it is reduced by what is actually recovered from the at-fault driver's bodily injury policies.
When the driver carried no insurance, or was never found
Your own uninsured motorist coverage responds, at the limits on your policy, and a hit-and-run driver counts as uninsured under 215 ILCS 5/143a. The police report matters here more than people expect, because it is the first thing your carrier asks for when it evaluates whether the collision happened the way you described it.
Underinsured coverage does not stack on top of the at-fault driver's policy. If the driver who hit you had $25,000 and you carry $100,000 in underinsured coverage, the ceiling on the whole claim is $100,000, not $125,000. His limit is not your limit, and the gap is what your own coverage is for.
Call (312) 492-7700or email
info@lsblaw.net
and we will read the declarations page with you.
Three Deadlines Run at the Same Time
Most people know there is a filing deadline. In an Illinois uninsured motorist claim there are three clocks, and only one of them comes from the statute of limitations.
- Two years from the date of the crash to sue the at-fault driver for personal injury (735 ILCS 5/13-202).
- A separate contractual deadline inside your own policy for demanding uninsured motorist arbitration, commonly two years from the crash and enforceable in Illinois. It is set by the policy rather than by statute, which is why the policy has to be read.
- Under 215 ILCS 5/143.1, that contractual period is tolled from the date you file proof of loss until your carrier denies the claim in whole or in part.
Notify your own carrier in writing before you settle with an underinsured driver
Before you accept a settlement from the at-fault driver's insurer, you must give your own carrier advance written notice. The carrier then has 30 days to advance the tentative settlement amount and preserve its subrogation rights, or lose them (215 ILCS 5/143a-2(6)). Sign the release first and you can forfeit the underinsured claim entirely. This is the single most common way a person handling a claim alone loses the coverage that was going to pay for the surgery.
What to Do in the Hours After a Driver Flees
The first night decides how much of this claim is provable. Take these steps in this order.
Step 1: Get medical care the same day
Go to the emergency room or an urgent care clinic before you go home. The gap between the crash and the first treatment note is the first thing an adjuster measures.
Step 2: Report the crash to the police that night
Your own carrier will ask for the police report, and in a hit-and-run it is the document that establishes there was another vehicle. Give the responding officer everything you remember while you still remember it.
Step 3: Write down whatever fragment you have
Two digits of a plate, a color, a dented rear quarter panel, a company name on a door. A partial description has identified fleeing vehicles in Chicago more than once, and it is worthless once it fades.
Step 4: Ask for camera footage this week, not next month
Businesses, residential buildings, parking structures and city cameras along the block record over themselves on cycles measured in days. We send footage requests as soon as we are retained, because the window is short.
Step 5: Tell your insurer this is a hit-and-run claim
A hit-and-run is reported and handled differently from an ordinary collision claim, and calling it in as a routine crash can start the file in the wrong place.
Call (312) 492-7700 or email
info@lsblaw.net before you give a recorded statement.
What a Claim Against Your Own Insurance Company Actually Looks Like
The adjuster on the other end of the line works for the company you have been paying premiums to, and is nonetheless adverse to you on the question of what the injury is worth. That is not bad faith. It is the structure of the coverage.
The file gets built exactly the way a liability case gets built. Medical records and bills, wage documentation, the police report, photographs, treating physician opinions on permanency, and where the injury required surgery, the operative reports and the cost of future care. Your carrier evaluates all of it as a defendant would.
If the amount is disputed, it is not decided by a Cook County jury. Under 215 ILCS 5/143a it goes to arbitration before the American Arbitration Association, in front of an arbitrator, on a record built by the lawyers. That is a different proceeding with different rules, and it rewards a file that was prepared for a hearing from the beginning.
Hit-and-Run Victims on Foot and on a Bicycle
Drivers flee disproportionately after striking someone who was walking or riding, and those claims run on the same uninsured motorist coverage. If you were struck as a pedestrian or on a bike, the coverage that responds is often your own auto policy, or a resident relative's, even though you were not in a car at the time.
The physical contact requirement in Section 143a applies to property damage recovery, not to your bodily injury claim. A cyclist struck by a car that never stopped still has an uninsured motorist claim for the fractures, the surgery and the time off work. We handle those claims alongside our
pedestrian accident and
bicycle accident work.
Claims We Have Taken to an Arbitrator and Through Surgery
$527,000 arbitration award for a cyclist with a fractured femur. Arbitration is the forum where a contested Illinois uninsured motorist claim is decided, and this is a published award from one.
$2.2 million recovery in a rear-end crash where a lumbar injury progressed to spinal fusion. Documented treatment is what separates a low offer from a full one.
We have practiced in Chicago since 1993 and we prepare every case as though it will be tried, or in a coverage claim, as though it will be argued in front of an arbitrator.
What This Costs You Before There Is a Recovery
Nothing. The case evaluation is free, we work on a contingency fee, and there is no fee unless we recover compensation for you. If your claim is against your own carrier, the fee arrangement is the same as it is in a liability case.
Questions People Ask After a Driver Leaves the Scene
What happens if the driver who hit me in Chicago is never found?
Your claim proceeds against your own insurance company. Illinois law treats a hit-and-run vehicle as an uninsured motor vehicle under 215 ILCS 5/143a, so the uninsured motorist coverage on your policy responds even though nobody is ever charged. You still have to prove how the collision happened and what the injury cost you, which is why the police report and same-day medical treatment matter so much.
Does my own insurance pay if an uninsured driver hits me in Illinois?
Yes, through the uninsured motorist coverage that every Illinois auto liability policy is required to carry. The claim is filed with your own carrier, and if the two of you disagree about coverage or about the value of the injury, the dispute goes to arbitration before the American Arbitration Association rather than to court.
How much uninsured motorist coverage am I required to have in Illinois?
At least $25,000 per person and $50,000 per accident, the bodily injury minimums in Section 7-203 of the Illinois Vehicle Code. Many drivers carry more than that without knowing it, and where uninsured coverage exceeds the minimums, 215 ILCS 5/143a-2 requires matching underinsured coverage on policies issued or renewed on or after December 1, 2004. Reading the declarations page is usually the first thing we do.
Do uninsured motorist claims in Illinois go to arbitration?
Contested ones do. Section 143a sends disputes over coverage and over the amount of damages to arbitration before the American Arbitration Association, so the case is decided by an arbitrator rather than a jury. There is also a deadline inside your policy for demanding that arbitration, commonly two years from the crash, which is separate from the two-year statute of limitations.
Can I settle with the at-fault driver's insurance and then pursue my underinsured claim?
Only if you give your own carrier written notice before you settle. Under 215 ILCS 5/143a-2(6) the carrier has 30 days after that notice to advance the tentative settlement amount and keep its subrogation rights. Signing a release without giving notice first can end the underinsured claim, so the sequence has to be right.
Talk to a Chicago Hit and Run Lawyer While the Evidence Is Still There
Camera footage overwrites, policy deadlines run, and the notice requirement that decides an underinsured claim comes due before any settlement is signed. We handle uninsured and underinsured motorist claims in Cook County and across DuPage, Lake, Will, Kane, McHenry and Kankakee counties, and if you cannot come to the office at 311 N. Aberdeen, we will come to you at home or in the hospital.
Call (312) 492-7700, email
info@lsblaw.net, or send us the details and an Illinois uninsured motorist lawyer will review your coverage at no cost.